Getting Your Credit Ready to Buy a Home
Queen Creek · Community Photo
If you're planning to buy a home in the next year or two, there's something worth doing well before you start looking at houses: getting your credit in shape.
Your credit affects whether you qualify, what loan programs are available, and what interest rate you're offered. And here's the part people underestimate — that rate applies to a very large loan over a very long time. Small differences add up to real money.
The good news is that credit responds to attention. Here's where to focus.
Know where you stand
Start by actually looking. You're entitled to free credit reports from the major bureaus through AnnualCreditReport.com, the official site authorized for this purpose.
Read them carefully. Errors are more common than people expect: accounts that aren't yours, balances reported incorrectly, items that should have aged off. If you find a mistake, dispute it. Correcting an error is one of the fastest ways to improve a score.
What actually moves the needle
Credit scoring is complicated, but a few factors carry most of the weight:
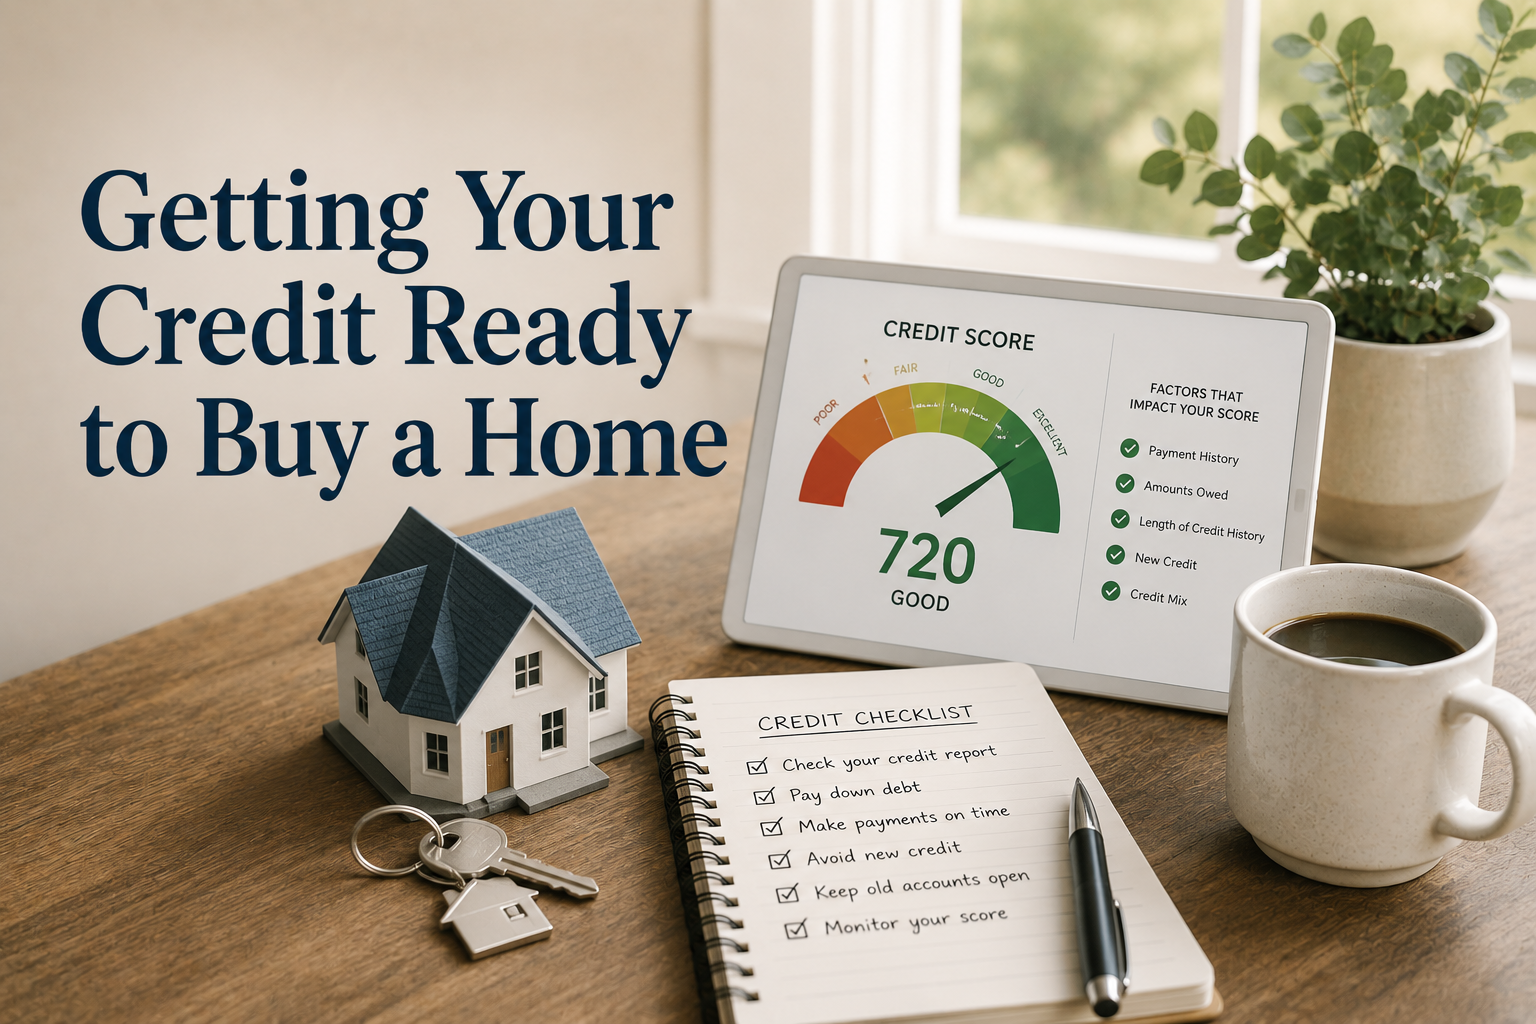
Payment history. This is the biggest one. On-time payments build your score; late payments hurt it, and recent lateness hurts more than old lateness. If you do nothing else, pay everything on time, every time.
How much of your available credit you're using. This is often called utilization. Carrying balances close to your limits tends to hurt, even when you pay on time. Bringing balances down relative to your limits can help meaningfully, and often fairly quickly.
Length of credit history. Older accounts help you. This is why closing your oldest credit card, which feels like tidying up, can actually work against you.
New credit applications. Each application can cause a small dip. A cluster of them in a short window looks like distress.
Mix of credit types. A modest factor, but variety helps.
What to avoid before applying
Once you're within a year of buying, a few habits protect you:
- Don't open new credit accounts, including store cards at checkout.
- Don't close old accounts, even ones you don't use.
- Don't finance a car, or anything else large, until after you close on the house.
- Don't let anything go late, even a small bill.
- Don't move large sums of money around without documentation, since lenders will ask about it.
That last one catches people by surprise. Lenders need to verify where your funds came from. A large unexplained deposit creates questions and delays.
Reducing debt helps twice
Lenders look at your debt-to-income ratio, which compares your monthly obligations to your monthly income. Paying down debt improves this ratio, which can improve what you qualify for. It often helps your credit score at the same time.
If you're carrying credit card balances, focusing there tends to be the highest-value use of extra money before buying.
Give yourself time
Credit improvement isn't instant. Some changes, like paying down balances, can show up within a couple of months. Others take longer.
This is why starting early matters. A buyer who begins preparing a year ahead has options that a buyer starting a month before applying simply doesn't.
Talk to a lender before you think you're ready
Here's advice a lot of people wish they'd gotten sooner: have the conversation early, even if you're not close to buying.
A loan officer can look at your actual situation and tell you specifically what would help most. Sometimes people discover they're in better shape than they thought. Other times they get a clear, concrete list of what to work on, which is far more useful than guessing.
The Consumer Financial Protection Bureau also offers free, unbiased resources on credit and home buying.
Matthew Baker with Guild Mortgage works with buyers in the Queen Creek area, including people who are still a year or more out from purchasing.
The work you do now pays for years
Getting your credit ready isn't glamorous. It's paying bills on time, chipping at balances, and resisting the urge to open a store card for 15% off.
But the payoff shows up in the rate you're offered and the payment you'll make every month for potentially decades. Few short-term efforts pay off that well.
Get in touch Matthew Baker — Guild Mortgage Website: https://bookspanbaker.com/ Email: matt.baker@guildmortgage.net
Helpful links
- AnnualCreditReport.com (free official credit reports): https://www.annualcreditreport.com/
- CFPB credit and homebuying resources: https://www.consumerfinance.gov/owning-a-home/